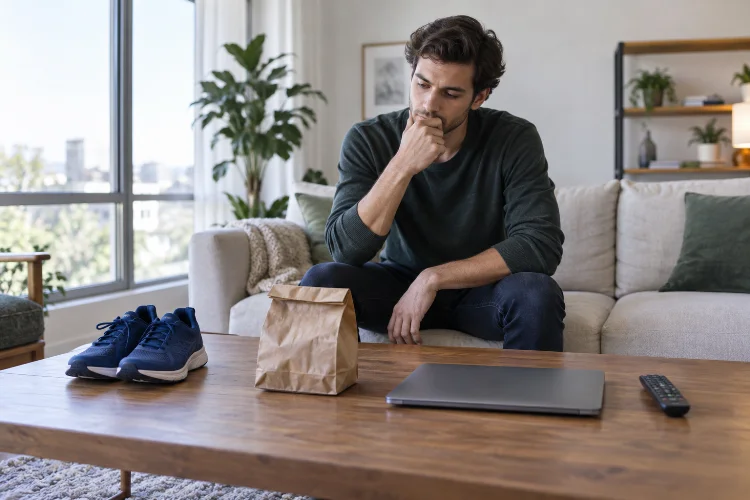
Every day, you make dozens of choices without thinking of them as economic decisions.
You decide whether to cook dinner or order takeout, spend Saturday working or relaxing, buy a new phone or keep your savings untouched, and even whether to watch another episode or go to bed.
Every one of those choices involves giving something up.
That hidden sacrifice is where opportunity cost comes in. Understanding Opportunity Cost in Everyday Life means recognizing that the real cost of a decision is not always the amount of money you pay.
It can also include lost time, missed experiences, forgone income, or another option you could have chosen instead.
Economists define opportunity cost as the value of the next-best alternative that is given up when a choice is made. It is closely connected to scarcity because people have limited time, money, and resources, so choosing one option usually means sacrificing another.
Once you start noticing opportunity costs, everyday decisions can look surprisingly different.
What Is Opportunity Cost?
Opportunity cost is the value of the best alternative you do not choose.
Imagine you have $40 available for entertainment. You could use it for dinner with friends or buy a new video game. If you choose dinner, the game becomes the alternative you give up.
The opportunity cost is not every possible thing you could have done with the $40. Economically, the focus is on the next-best alternative-the option you valued most after the one you selected.
This distinction matters because people often think only about visible costs.
If dinner costs $40, the financial price is obvious. But the economic cost also includes what that money could have provided instead.
Opportunity cost can therefore involve money, time, comfort, enjoyment, income, or future benefits.
Why Does Every Choice Have an Opportunity Cost?
Opportunity cost exists becuase resources are limited.
You have a limited income. A company has limited employees and equipment. A government has a limited budget. Most importantly, everyone has only a certain amount of time.
Economics describes this broader condition as scarcity. Because people cannot pursue every possible option simultaneously, they must make trade-offs.
Suppose you spend two hours scrolling through social media in the evening.
Those two hours may appear free because no money leaves your bank account. However, they could have been used to exercise, study, sleep, work on a side project, meet friends, or simply relax in another way.
Your opportunity cost depends on which of those alternatives you would have valued most.
This is why economists often say that even something described as “free” may still carry a cost. Your time and attention have alternative uses.
Everyday Examples of Opportunity Cost
The concept becomes much easier to understand when you connect it to normal situations.
1. Spending vs. Saving Money
Suppose you receive a $1,000 bonus at work. You decide to spend it on a vacation.
The direct cost is $1,000. But there may also be an opportunity cost.
You could have placed that money in savings, paid down debt, invested it, purchased a laptop, or used it for professional training. If investing was your most valuable alternative, the benefits you might have earned from that investment form part of the opportunity you gave up.
That does not mean taking the vacation was a bad decison. Opportunity cost does not tell you that you must always choose the option with the largest financial return.
It simply makes the trade-off visible.
2. Working vs. Taking Time Off
Imagine you can work an extra Saturday shift and earn $150.
Instead, you attend a family event.
From a purely financial perspective, the lost $150 is part of your opportunity cost. But if spending time with family is personally more valuable to you, attending the event may still be the better choice.
Economic decisions involve value, and value is not always measured entirely in dollars.
3. College vs. Full-Time Work
Education offers another classic example.
The cost of attending college includes more than tuition, books, housing, and transportation. A student may also give up wages that could have been earned by working full-time during those years.
OpenStax specifically notes that opportunity cost can extend beyond direct monetary expenses and include time or other resources that must be sacrificed.
The comparision between education and employment shows why evaluating only the price tag can underestimate the real economic cost of a choice.
Opportunity Cost Is Not Always About Money
One of the biggest misconceptions is that opportunity cost must involve cash.
It does not.
Consider someone who has three free hours on Sunday afternoon. They could exercise, visit relatives, watch a movie, learn a new skill, or sleep.
No purchase is required, but choosing one activity removes the opportunity to spend those same three hours on another.
Time is especially important because it cannot be stored and used later. Once an hour has passed, it is gone.
This makes time management an excellent example of opportunity cost in daily life.
You can apply the idea to productivity as well. Spending four hours polishing a relatively unimportant task may prevent you from completing another project with a much larger impact.
The question becomes: What valuable alternative am I giving up by spending my time here?
That can be a useful way to rethink your daily priorites.
Opportunity Cost vs. Sunk Cost
Opportunity cost is sometimes confused with sunk cost, but they are very different concepts.
A sunk cost is a cost that has already occurred and cannot be recovered. Opportunity cost looks forward toward the alternatives available from your current position.
Suppose you buy a $30 concert ticket. On the day of the event, you feel exhausted and would rather stay home.
The $30 is already spent and may be non-refundable. That makes it a sunk cost.
Your current choice should focus on the value of attending the concert compared with the value of staying home, not simply on the fact that you already paid for the ticket.
OpenStax describes sunk costs as past costs that cannot be recovered, whereas opportunity cost measures what is sacrificed when resources are used in a particular way.
Separating these ideas can help prevent the common habit of continuing with a poor decision simply because money, time, or effort has already been invested.
How to Calculate Opportunity Cost
Opportunity cost is often expressed with a simple idea:
Opportunity Cost = Value of the Best Alternative Forgone
In some situations, calculating it is straightforward.
Imagine you own a small apartment that could generate $800 per month if rented out. Instead, you use it as an office for your business.
Even if you do not physically pay $800 each month for office space, you are giving up $800 in possible rental income.
That lost income represents an implicit cost of using the apartment yourself. OpenStax explains that economic analysis can include implicit costs—the value of alternative uses of resources already owned by a business.
In everyday life, exact calculations may be harder because alternatives can involve emotional or personal value.
For example, how much is an afternoon with your family worth compared with four hours of paid overtime?
There may be no perfect numerical answer.
The goal is not always to calculate an exact dollar amount. Sometimes simply identifying the next-best alternative is enough to improve the decision.
How Opportunity Cost Helps With Better Decisions
Thinking about opportunity cost encourages you to compare options instead of evaluating choices in isolation.
Suppose you are considering buying a $1,500 smartphone.
Instead of asking only, “Can I afford it?” you might ask:
“What else could I do with $1,500?”
Perhaps you could keep your current phone and use the money for travel, debt repayment, investing, education, or an emergency fund.
This does not automatically mean that buying the phone is wrong. If the new device significantly improves your work or quality of life, it might genuinely be the option you value most.
Opportunity-cost thinking is about making the trade-off deliberate rather than invisible.
Econlib notes that the concept is powerful precisely because using a resource for one purpose means giving up the value of its best alternative use.
Before making an important choice, try asking three questions:
What am I choosing? What is the best alternative? Which option gives me more value based on my current goals?
That simple process can improve financial, career, and lifestyle decisions.
Opportunity Cost in Business and Career Decisions
Businesses deal with opportunity costs constantly.
A company with $100,000 available might use it to hire employees, launch an advertising campaign, upgrade equipment, develop a new product, or keep additional cash reserves.
Choosing one project means delaying or rejecting another. Opportunity cost also matters when entrepreneurs use resources they already own.
A business owner who works full-time without paying themselves a salary may appear to have lower accounting expenses, but their time still has economic value because they could potentially earn income elsewhere.
Career decisions work in a similar way.
Accepting a higher-paying job may mean giving up flexible hours. Staying with a comfortable employer may mean passing on faster career growth elsewhere.
The “best” choice therefore depends on more than salary.
Income, flexibility, learning opportunities, commute time, stress, job security, and personal goals can all affect the real trade-off.
Understanding opportunity cost can change the way you look at ordinary decisions. The concept reminds us that choosing something usually means giving up another valuable option, whether the resource involved is money, time, energy, or attention.
The key is not to obsess over every alternative you miss. Instead, focus on the next-best option and ask whether your current choice provides greater value.
Opportunity cost can help with budgeting, career planning, time management, education, business decisions, and even simple weekend plans.
The next time you face an important choice, do not ask only, “What will this cost me?” Ask, “What am I giving up by choosing this?”
That question can reveal the real trade-off-and help you make decisions that better match your goals.